Blog

  • How Research Trips Provide an Edge to our Investment Process

    How Research Trips Provide an Edge to our Investment Process

    For the MCP team, 2024 has been a productive year, highlighted by extensive research trips to key markets which we believe provide us with a competitive edge. In-person meetings with portfolio and pipeline companies, local experts, policy makers and private equity houses have provided invaluable insights into macroeconomic and geopolitical trends, businesses’ operating conditions and corporate governance, as well as enabling in-person engagement. Additionally, in under-researched emerging markets, where stocks can be mispriced due to limited available information, these trips are essential for uncovering high-quality investment opportunities that have the potential to deliver significant alpha.

    The Importance of a Strong Network

    We believe the key to successful research trips lies in having a trusted and extensive network. Our 25-year network is built on Portfolio Manager Carlos Hardenberg’s decades of experience in emerging markets and complemented by the industry relationships built by MCP’s analysts throughout their careers.

    We don’t expect our analysts to be experts in everything, but we do expect them to know where to access relevant information, including identifying key contacts during research trips. Building these robust networks—and leveraging the valuable insights they offer—drives our commitment to frequent research trips, which in turn, creates further opportunities to engage with local experts and businesses, continually expanding our network. We adopt a targeted approach to our research trips, customising each trip to align with the unique macroeconomic and geopolitical conditions of the region and the specific characteristics of the opportunity set. This allows us to gain a deeper understanding of both country- and sector-specific challenges. Furthermore, our priority is to visit regions where we hold a strong investment conviction and have a higher portfolio exposure, leading to the majority of our trips being concentrated in Asia.

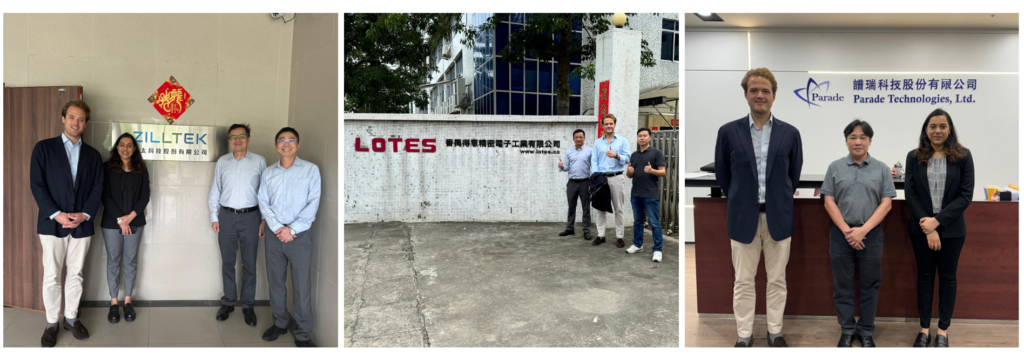
    For example, during a research trip to Greater China in Q2 2024, in Taiwan, our highest country exposure, the team prioritised meeting with portfolio companies’ management teams and actively driving engagement. When the team continued to mainland China, they focused on conducting visits to manufacturing facilities of portfolio companies with operations in the region. In contrast, when the team visited Vietnam in Q3—where our exposure is just 3%— they prioritised exploring new opportunities through meetings with pipeline companies and local experts, which ultimately led to the addition of a new holding, FPT.

    Looking Beyond the Sell-Side

    In today’s investment landscape, it is all too easy to believe you have all the information you need at the click of a finger. When investing in well-known highly liquid stocks, information is readily available through sell-side reports, online resources and advanced data platforms such as Bloomberg. However, the ubiquity of this information leaves little room for competitive knowledge advantage in what are highly efficient markets. Moreover, relying solely on sell-side information often overlooks the depth, nuance and context that can only be gained through on-the-ground research.

    In contrast, our focus is on identifying and understanding lesser-known companies. By concentrating on mid-cap stocks in emerging markets, we operate in a universe that is often under-researched, with limited sell-side coverage, reduced visibility and minimal overlap with major benchmarks. This lack of broad market coverage often leads to mispricing, creating opportunities to generate alpha by identifying undervalued companies with strong fundamentals. However, investing in these types of unknown stocks also demands rigorous, independent, in-person channel checks. While conducting this research, our team maps the competitive landscape, evaluates total addressable market (TAM) opportunities and stays informed about sector innovation and R&D trends.
    Therefore, for our investment strategy, conducting research trips is not just beneficial—it is essential. These trips allow us to look for hidden opportunities, gain insights that others might overlook, and capitalise on market inefficiencies with the aim to generate additional sources of alpha.

    Company Case Study: Chroma

    The Greater China trip in Q2 2024 exemplifies how a well-structured research trip can profoundly enhance our understanding of a portfolio company. During this trip, the team focused on Chroma, a Taiwanese equipment supplier and a recent addition to the portfolio. Spending several weeks immersed in Taiwan’s vibrant semiconductor ecosystem, the team conducted comprehensive channel checks on Chroma.
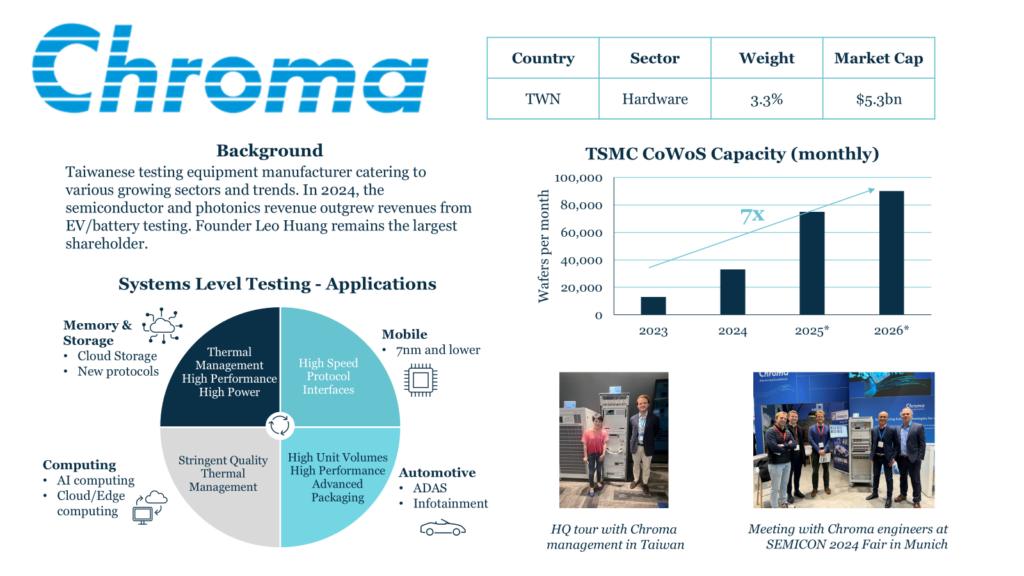
    Source: Chroma, Bloomberg, CLSA

    Traditionally a manufacturer of testing equipment for EV and battery applications, Chroma has leveraged its expertise in thermal management to establish a foothold in the niche market of systems-level testing for high performance computing chips (HPC).

    Through formal meetings, campus tours and discussions with technical experts, MCP gained deeper insights into the demand dynamics for Chroma’s innovative products. A standout example of its innovation-driven approach is the development of a cutting-edge metrology tool designed for a leading foundry’s advanced packaging process. This breakthrough positions Chroma to capitalise on the foundry’s rapid capacity expansion, driven by the growing demand for CoWoS (Chip-on-Wafer-on-Substrate) technology as the AI/HPC boom accelerates.

    Enhancing Geopolitical & Macroeconomic Insights

    Over the past year, the MCP team has visited India on several occasions, Greater China— including Taiwan, Hong Kong, and mainland China—as well significant portions of ASEAN, including Vietnam, Malaysia, Thailand and Singapore. As well as providing company-specific insights, in-person visits help us to assess the broader environment and challenges that companies operate in by providing a deeply informative perspective on each country’s macroeconomic landscape and enabling us to closely monitor risks, including regulatory changes and geopolitical tensions. Based on observations from recent on-the-ground trips to Greater China, we believe that the likelihood of a Chinese invasion of Taiwan in the short term appears low, given the substantial domestic economic challenges China is currently facing. However, we continue to monitor the situation very closely.

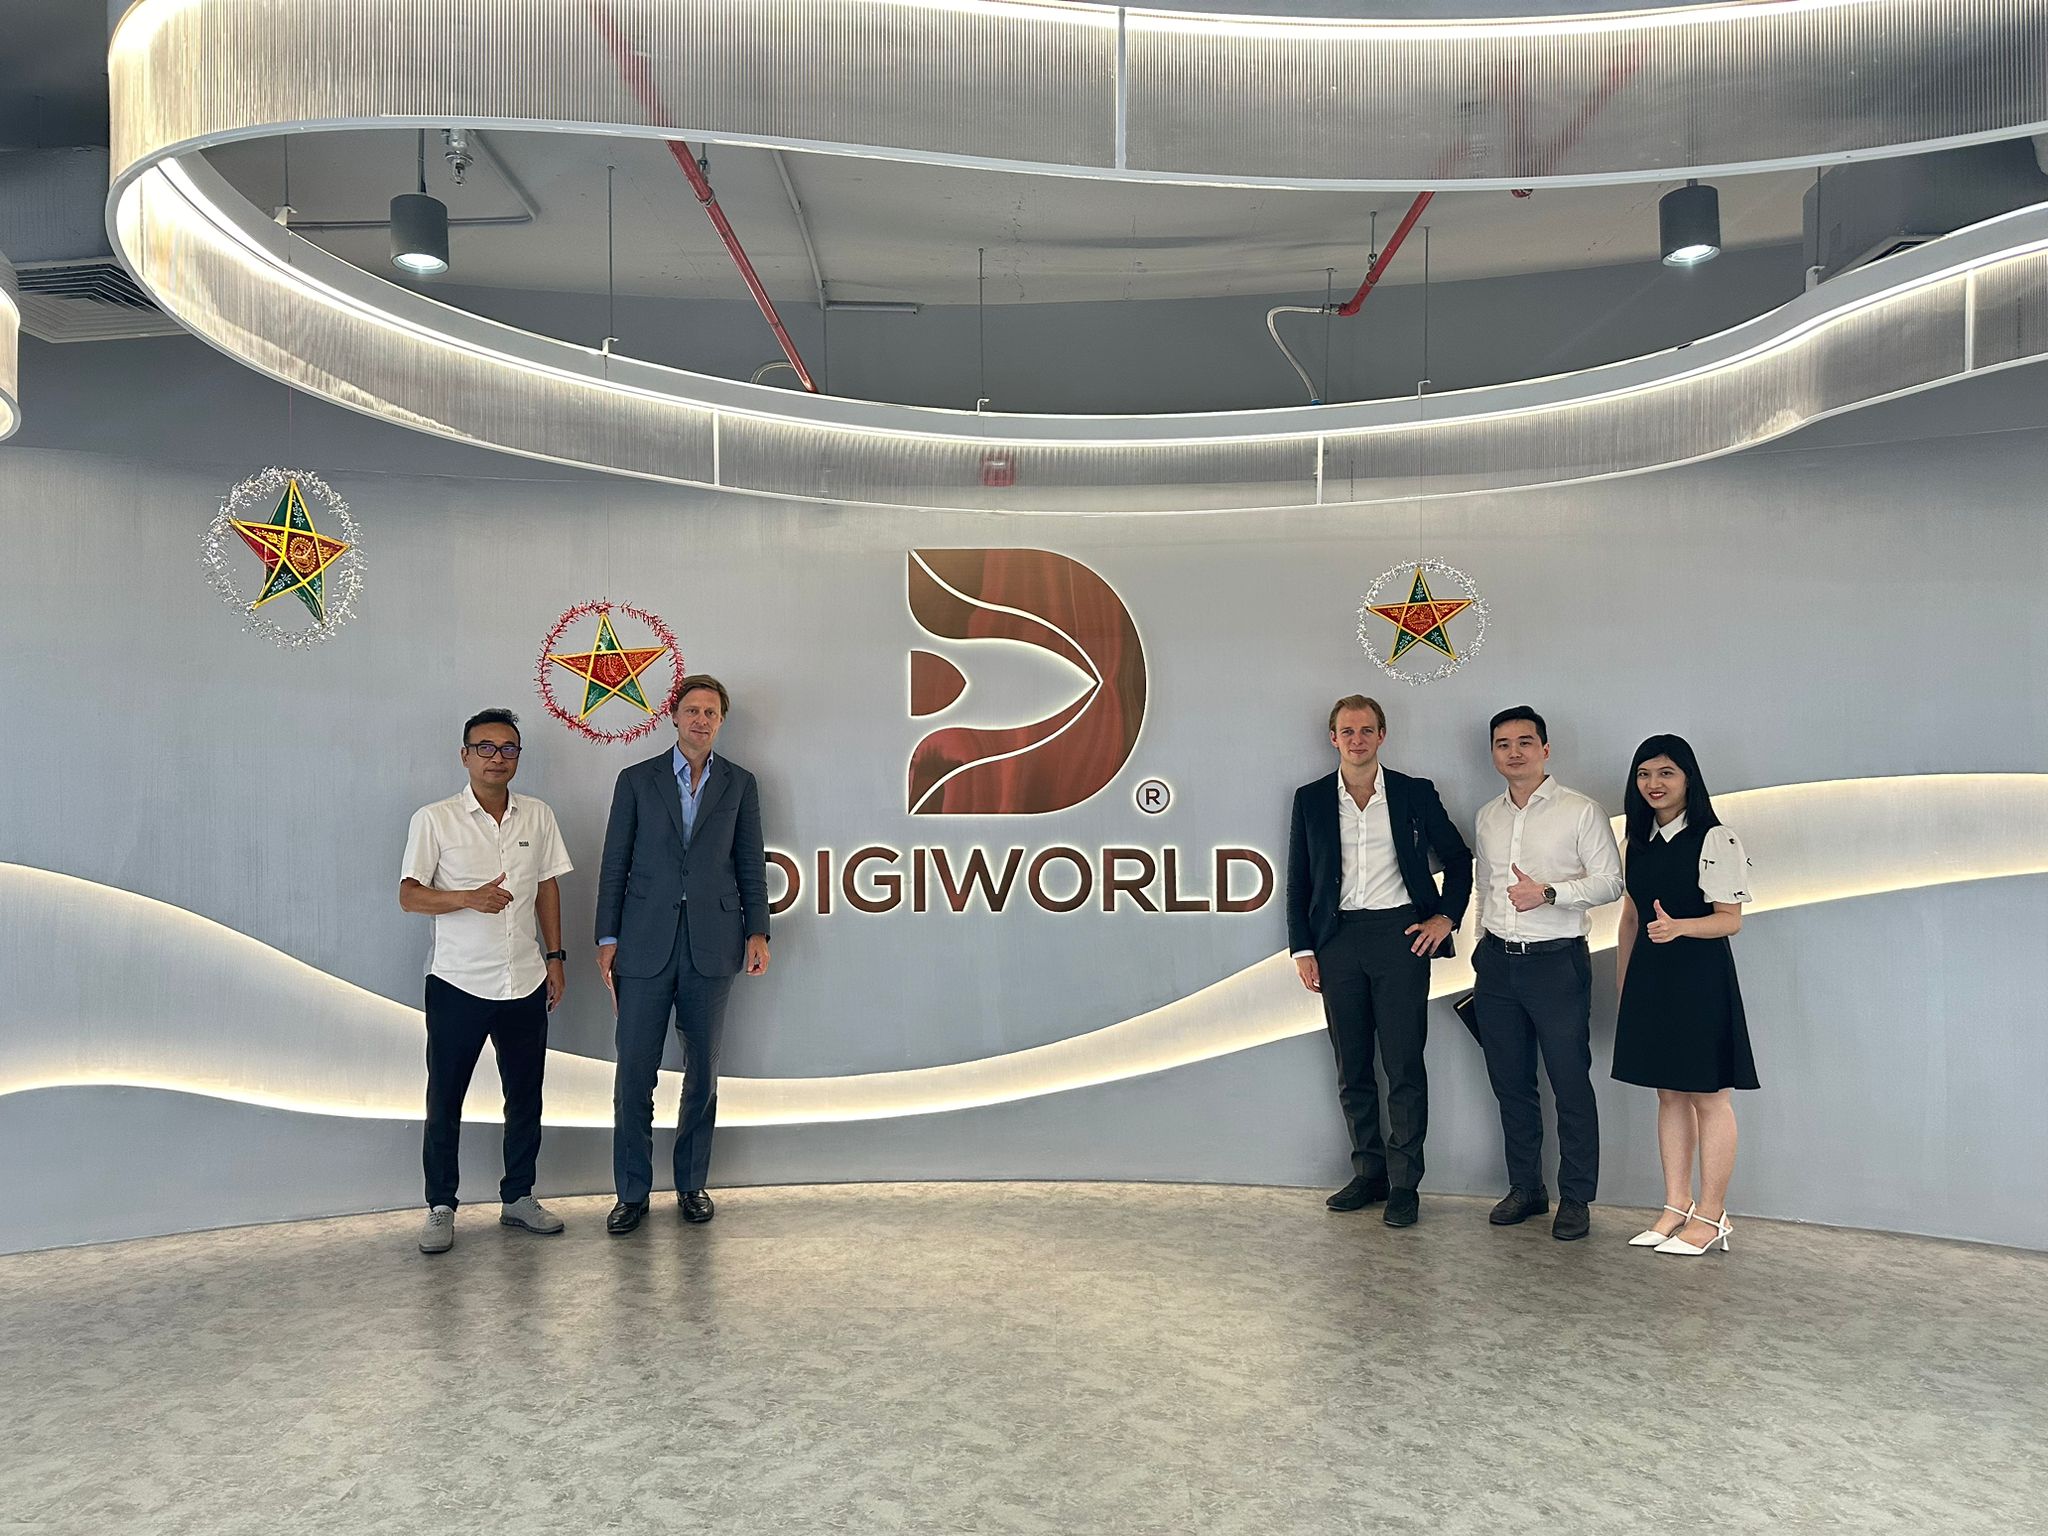
    As we move into 2025, we do so with a strengthened bullish conviction in ASEAN, particularly in Vietnam, following the team’s visit to the country in September. Leveraging Carlos’ extensive network, the trip provided access to company founders, entrepreneurs, local private equity leaders, government officials, former colleagues and numerous businesses. The team also visited a local tech university and even test-drove the new VinFast car through the streets of Hanoi.

    These meetings and conversations, combined with Carlos’ two decades of experience traveling to Vietnam, highlighted the country’s remarkable pace of technological innovation and transformation—an insight that stood out as the trip’s primary takeaway. Everyday observations further reinforced this perspective, from the widespread use of Grab (Asia’s version of Uber) as the primary mode of transportation, to seamless digital payments via Apple Pay.
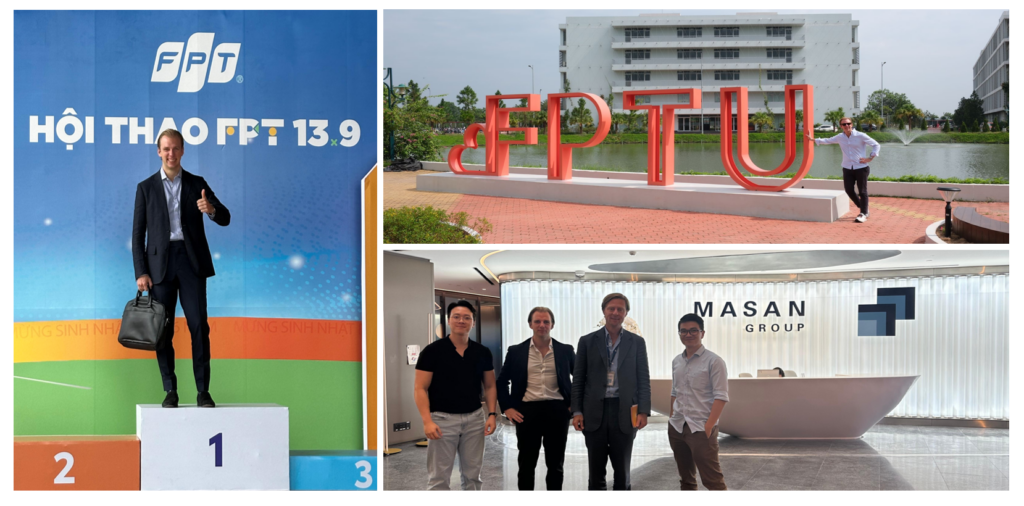
    Other key takeaways highlighted Vietnam’s impressive, world-class infrastructure—spanning airports, roads, and bridges — a business-friendly government, and significant strides in corporate governance. Collectively, these factors reinforced our optimistic view of the country’s strong growth trajectory, which we believe will support its transition to emerging market status.

    Opportunities in ASEAN: Example Vietnam
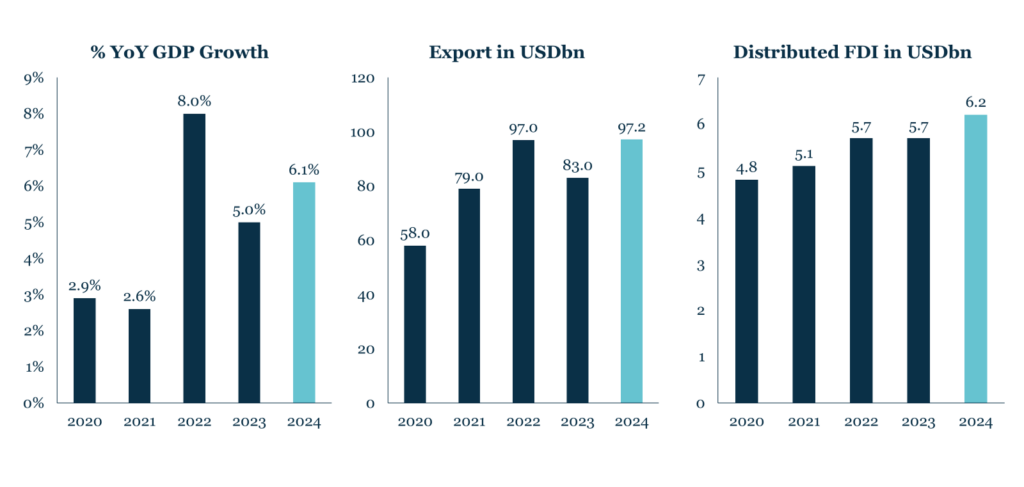
    Source: Maybank Research, Bloomberg, local sources, IMF WEO October
    2024, FT, Export and FDI figures as of Q2 of each year

    While we are excited about opportunities in Vietnam, our core convictions remain in India, Taiwan and South Korea. Research trips to these regions have reinforced our convictions, highlighting the innovation of local companies, strong corporate governance practices and supportive macroeconomic environments. India’s well-educated, youthful population supports long-term growth, while Taiwan and South Korea lead in innovation, particularly in tech sectors such as AI, 5G and renewable energy, where we favour asset-light, IP-based businesses.

    Although South Korean President Yoon Suk Yeol shocked the nation and global investors with his failed attempt to impose martial law in December, we believe the Constitutional Court’s decision to impeach Yoon, leading to his arrest in January 2025, highlights the strength of the country’s democratic framework which will allow the country to focus on its economic potential. Fundamentally, we remain confident in the country’s stability and its promising investment opportunities, particularly in the export market.

    Conclusion

    In 2025, the team is excited to continue these on-the-ground research trips to both familiar and unfamiliar markets. Trips already planned include India, Taiwan and Latin America, with additional trips to follow later in the year. These visits will allow MCP to conduct in-depth channel checks on portfolio companies, perform rigorous due diligence on pipelines companies, stay attuned to evolving macroeconomic and geopolitical trends, and conduct in-person engagement.
  • What Does Donald Trump’s Inauguration Mean for Emerging Markets?

    What Does Donald Trump’s Inauguration Mean for Emerging Markets?

    Donald Trump’s inauguration yesterday following his landslide victory marks a pivotal shift for U.S. and global markets. While U.S. equities and the dollar have strengthened in response, emerging markets face a more uncertain outlook due to Trump’s aggressive tariff rhetoric.

    Yet, within challenges lie opportunities. Countries like India, Indonesia, and Vietnam, for example, are already benefiting from the “China+1” strategy and appear well-positioned to attract new manufacturing investments. Their competitive labour markets, improving infrastructure, and supportive government policies make them increasingly appealing as companies seek to diversify supply chains and reduce dependency on China.

    At the same time, the U.S.’s heavy reliance on imports, particularly from China, reduces the likelihood of sweeping tariffs, which could risk significant domestic disruption. Trump refrained from threatening immediate tariffs on China in his first days in office, and even spoke by phone with President Xi Jinping just days before his inauguration, suggesting that tariffs on China could be more moderate than Trump advocated on the campaign trail. Nevertheless, Trump’s past track record and rhetoric on trade raises the possibility of bold policy shifts that may reshape global trade dynamics in the years to come.

    Emerging markets have previously responded to the above dynamics with increased trade diversification and reduced reliance on the US dollar. During the 2018 trade war, for example, China shifted imports like soybeans to Brazil, a move that fuelled record bilateral trade. This pattern could reemerge under Trump’s renewed tariff threats.

    Additionally, nations such as India are advancing local currency trade agreements, fostering resilience against external shocks. Intra-EM trade, particularly within Asia, has also grown significantly and is poised to accelerate further, offering emerging markets the chance to deepen their autonomy and global influence.

    Overall, while risks are evident, emerging markets could leverage this period of transition to strengthen resilience, diversify trade, and attract investment, positioning themselves as key drivers of global growth in the years ahead.

  • On-The-Ground In Vietnam

    On-The-Ground In Vietnam

    In the sixth episode of Insiders and Outliers, Carlos Hardenberg, founder and portfolio manager of MCP, explains how on-the-ground research trips add an edge to MCP’s investment process, and draws on his recent visit to Vietnam to unpack the country’s rapid economic growth over the past few decades. He shares key insights into Vietnam’s vibrant technology sector, its rapid digitisation, its emergence as a manufacturing hub, and the addition of a new high-conviction Vietnamese holding following the trip.

    To see our Podcast Policy go to www.mcp-em.com/podcast-policy

  • Trump’s Victory: Uncovering the Silver Linings for Emerging Markets

    Trump’s Victory: Uncovering the Silver Linings for Emerging Markets

    The Global Spotlight on Trump’s Victory

    The world’s attention is fixed on the outcome of what many have called one of the most divisive U.S. elections in recent history. Yet the results are anything but close, with a Republican sweep across the Senate, likely the House of Representatives, and, of course, the presidency, secured by Donald Trump. Businesses and governments worldwide are now asking how a second Trump presidency will affect them. Given Trump’s notorious unpredictability, the answer for many is not straightforward. At MCP, we’re asking the same for Emerging Markets and, despite the often pessimistic narrative, we’ve identified several potential silver linings in a Trump presidency.

    Trump’s Domestic Economic Policies:

    Trump positions himself as a champion of “the people,” and if that term refers to America’s wealthiest individuals and business leaders, he may be right. A central pillar of his domestic economic agenda is tax cuts, and with a Republican majority, an extension of the 2017 Tax Cuts & Jobs Act is highly likely. This act established a flat corporate tax rate of 21% and lowered individual tax rates, with the wealthiest Americans seeing the greatest benefit. Additionally, Trump has consistently advocated for deregulation, especially in sectors like digital assets and non-renewable energy.

    Much like the pre-election polls, economists are divided on whether Trump’s next term will ultimately harm or hinder the U.S. economy in the long term. However, there is general consensus that, in the short term, Trump’s pro-business policies are likely to stimulate US economic growth. Herein lies the first silver lining for EM: a strong US economy has positive spill over effects on the global economy as it boosts demand from U.S. consumers for EM exports.

    Trump, Trade and Tariffs:

    However, the subject of Trump and trade is particularly sensitive for EM and Trump’s clear ‘America First’ stance is hard to ignore. Trump has been outspoken about his support for tariffs, yet both DM and EM may be left out in the cold as Trump has threatened a universal 10-20% tariff on all trading partners and indicated replacing income tax with tariff revenue via the proposed “Trump Reciprocal Trade Act.” That being said, China will clearly be the most effected with Trump advocating for a 60% tariff on Chinese imports.

    It may be wise not to take such threats at face value. Trump himself has described tariffs as a powerful negotiation tool and he might actually use them as such. The reality is that the U.S. remains heavily reliant on imports, particularly from China, whose production capacity is unparalleled. Although there is momentum behind reshoring manufacturing, reducing the U.S.’s global trade deficits through this approach is likely a long-term endeavor, potentially spanning decades. This economic interdependence could restrain Trump’s ability to impose sweeping punitive trade measures without risking inflation and considerable supply chain and economic disruptions domestically.

    Differing Impact on EM Regions:

    While finding a silver lining in China itself may be challenging, it’s much easier to spot ones in countries like India, Indonesia, Vietnam, Malaysia, and Mexico. These nations, known for their low-cost manufacturing, are set to become even more attractive to FDI as the global shift to “China+1” accelerates. As higher tariffs on China undermine its cost competitiveness, supply chain gaps will emerge, offering these countries opportunities to meet the demand and capture a larger share of global manufacturing. This increase in production could help offset the negative effects of higher tariffs on their exports to the U.S.

    Moreover, escalating U.S.-China trade tensions could create opportunities for other EM to strengthen their trade relationships with China. For example, during the trade war in 2018, China shifted from importing U.S. soy beans to sourcing them from Brazil. Similar patterns of retaliation could benefit countries with strong trade ties to China or those that produce goods that can replace US exports.  

    Resilience in EM:

    Emerging Market companies have demonstrated their resilience, thriving even amidst geopolitical and economic uncertainties, thanks to robust business models, innovation, and strong growth prospects. Structural advantages such as favourable demographics, higher GDP growth projections, and ongoing digitalisation ensure that EM will remain competitive, despite potential tariff-related challenges.

    While Trump’s presidency introduces a degree of unpredictability, more clarity over Trump’s intentions in the months ahead along with administration appointments is expected to reduce short-term market volatility. Although Trump’s policies pose risks to the global trade order, the outlook for EM is not all doom and gloom. In fact, certain EM regions stand to benefit from new growth and investment opportunities stemming from shifts set to accelerate under Trump such as China+1. We are confident that this resilient asset class will navigate these turbulent times as effectively as it did during Trump’s first presidency, during which the MSCI EM Index delivered a 57% return in USD terms1.

    1 Bloomberg: From 20 January 2017 – 20 January 2021

  • Navigating Market Swings: Reflections on Volatility in Investing

    Navigating Market Swings: Reflections on Volatility in Investing

    Navigating Market Swings: Reflections on Volatility in Investing

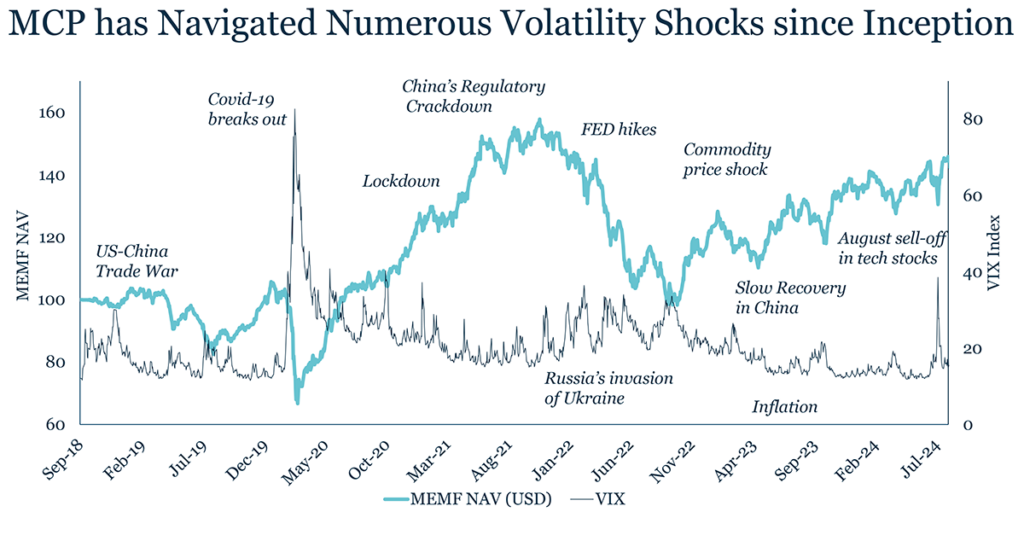
    Navigating volatility has always been a priority for the MCP investment team, not just to mitigate risks but also to proactively capitalise on the opportunities that market fluctuations present. Given the recent spike in volatility this summer, we thought it was an opportune time to share our insights on navigating market turbulence, drawing on Carlos Hardenberg’s 25+ years of experience. Beginning his career during the Asian financial crisis, Carlos has navigated the dotcom bubble, the global financial crash, the Covid-19 pandemic and numerous other market disruptions. His experience as a long-only equities investor has only reinforced the idea that volatility can be your friend if you use it effectively.

    Understanding Volatility

    Managing market volatility starts with understanding its causes — asking why investors buy one day and sell the next, often without any significant change in fundamentals. This behaviour is rooted in the fear of the unknown, a human characteristic to which investors are not immune.

    Source: Bloomberg. As of 30 September 2024.

    Uncertainty leads to nervousness, causing a risk-averse instinct which, in investing, often leads to sell-offs. The herd mentality exacerbates the situation — as everyone else sells, the fear of being left behind and suffering greater losses grows stronger, pushing more investors to follow suit. The widespread use of algorithmic trading, most of which trades on the same set of predefined conditions that mirror market movements, compounds the effects of sell-offs and thus increases volatility further. In 2018, Select USA estimated that algorithms now dominate 60-75% of trading in major US, European and Asian markets.

    Leveraging Volatility

    In times of volatility, we believe it is important to remain calm and focus on fundamentals and the long-term. We seek high-quality companies with excellent management teams, strong moats, positive cashflows and little to no debt. These companies are more likely to prove resilient and maintain a positive outlook. Nevertheless, we always monitor macro developments and their potential impact on our investment case very closely. Timing is critical in responding to changing macro and micro conditions — selling too early or too late can have significant consequences. Yet 25 years of investment experience has taught Carlos that selling on volatility alone usually leads to poor investment decisions. During the 2008 global financial crisis, many investors fled risk assets such as emerging markets, resulting in a vast pool of undervalued EM stocks despite their strong fundamentals and sound business models. Rather than following the herd, Carlos leveraged the volatility as a source of additional alpha generation. By staying disciplined, closely monitoring his investments and adjusting his strategy when needed, he was well positioned to capitalise on these mispriced assets during the subsequent recovery, thereby leveraging uncertainty as a friend. Similarly, during the Covid-19 pandemic, the team swiftly repositioned the portfolio, seizing the opportunity to add high-quality companies from our watch list. These companies were being unfairly dragged down by market sentiment. This timely and strategic response, we believe, contributed significantly to the fund’s strong outperformance.

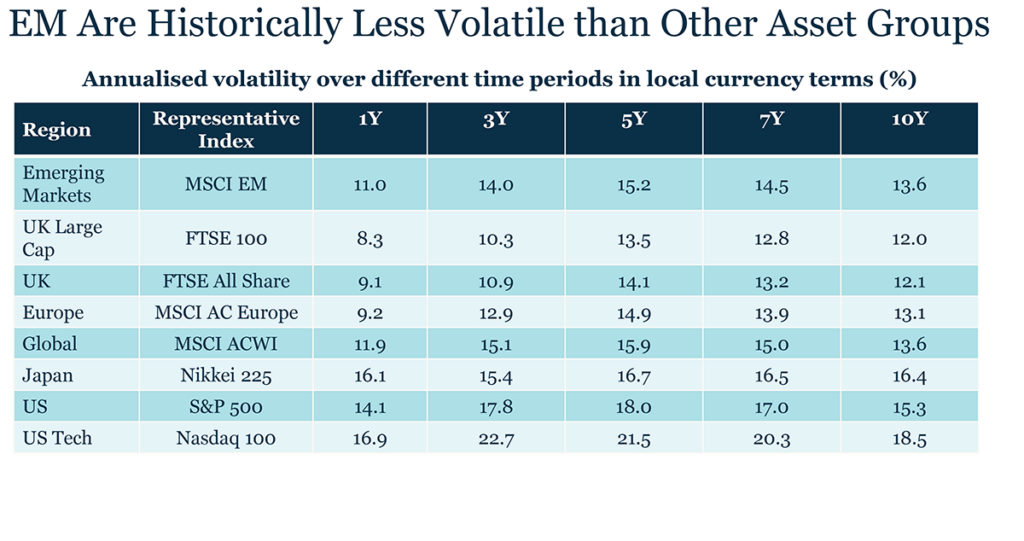
    Interestingly, over the past decade, US equities have been more volatile than emerging markets in local currency terms. One reason could be the high concentration of the US market. Since 2014, big tech companies have rapidly increased their market dominance, with the ‘Magnificent 7’ now accounting for around 30% of the S&P500. In a highly concentrated market, sell-offs can become more severe as many investors rush to offload the same stocks, leading to outsized losses for those who remain invested. Historical examples have showcased the risks inherent in highly concentrated markets. For example, the dotcom bubble era was dominated by five tech stocks, which were quickly sold off when the bubble burst, contributing to the 78% loss in the Nasdaq index from its peak in March 2000 to its low in October 20021.

    Source: FE Analytics

    Market Concentration and Volatility

    While the high concentration of the US market is widely recognised, many investors do not realise that the situation is similar in emerging markets. In the MSCI EM Index, the top 10 companies account for approximately 25% of the total index weight, despite there being around 1,300 constituents in total. In addition, many of the bulge-bracket EM funds’ portfolios are similarly concentrated in these top 10 names, potentially increasing their vulnerability to significant drawdowns during market sell-offs. This highlights the importance of portfolio diversification. We prefer smaller, lesser-known innovative companies in emerging markets, particularly in sectors like AI and the semiconductor supply chain, which we believe have a strong potential to deliver alpha.

    Monetary Policy, Volatility and Emerging Markets

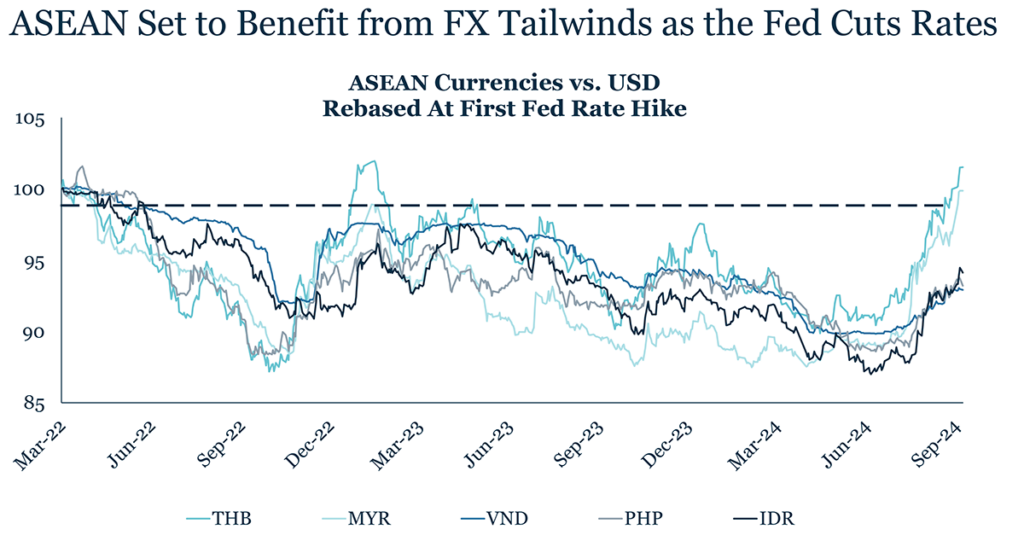
    One of the main sources of volatility this year has been the Federal Reserve’s decisions regarding interest rate cuts. While the pace of future cuts and any unexpected employment or inflation data may continue to cause market fluctuations, the direction is now clear with the first cut behind us. Our focus, however, remains on the impact of these rate cuts on emerging markets rather than the short-term volatility around Fed meetings. With rates trending lower, as demonstrated by the Fed’s half-point cut on 18 September, we believe emerging markets are poised to benefit. Lower interest rates in advanced economies typically weaken the dollar, which in turn supports EM currencies and eases the burden of dollar-denominated debt.

    Since 1988, EM equities have, on average, outperformed DM equities in 4/5 Fed rate-cutting cycles returning 29% in the 24 months following the last Fed rate hike2. Moreover, while many LatAm countries are ahead in the rate cutting cycle, Asian countries have been more cautious. Fed cuts now give many of them more room to begin their respective cutting cycles, thereby enabling cheaper borrowing, improving consumer sentiment and corporate spending, and stimulating growth.

    Source: Maybank Research, Bloomberg, local sources. As of September 2024.

    In addition, lower US interest rates can benefit emerging markets by reducing the attractiveness of safer, lower-yielding assets in developed markets, encouraging investors to seek higher yields in EM, increasing FDI flows and supporting EM asset prices. However, this impact varies across emerging markets as increased risk appetite and lower US yields cannot offset poor macroconditions or weak corporate fundamentals. For example, in the rate-cutting environment of 2019, Taiwan saw strong FDI inflows of $8.2bn, up 16% from 2018, while Argentina, with weaker fundamentals saw a 43% drop in FDI to $6.7bn3. Therefore, maintaining a robust macroeconomic overlay, combined with diligent stock selection, remains essential. This approach focuses on companies with strong fundamentals and resilient business models that can capitalise on a lower interest rate environment.

    Volatility around Elections

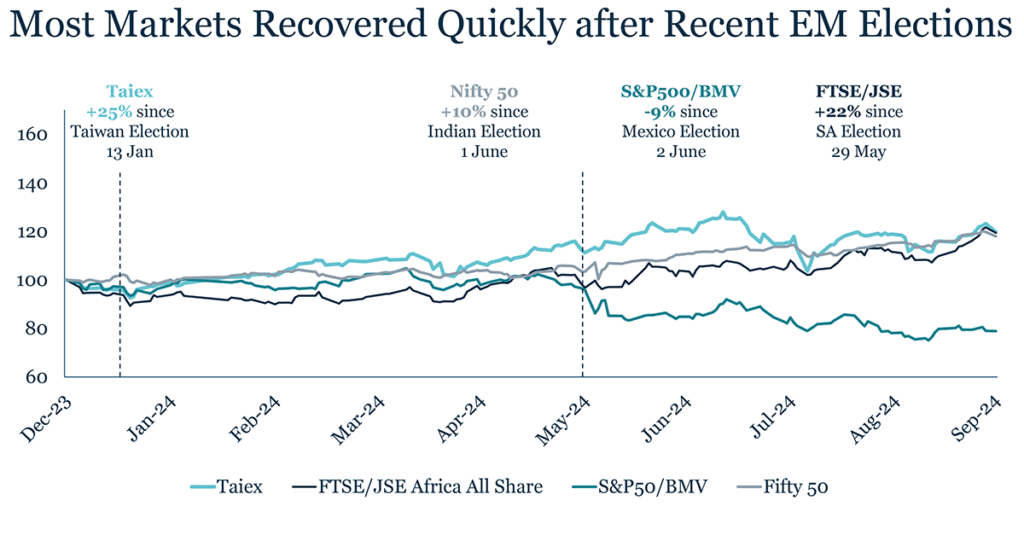
    The global election year, seeing more than 60 countries and two billion people participating in elections4, has provided an additional source of volatility as uncertainty over new governments and policy directions incites investors’ fear of the unknown. However, most of the elections in emerging markets this year have not led to significant long-term spikes in volatility as the results have largely maintained the status quo in government policy. While initial declines in equity markets were mostly brief and quickly reversed (Mexico being one exception) some elections have even reduced local market volatility, with South Africa being a good example.

    The US election remains a major source of uncertainty, more so than local EM elections, and will probably cause short-term market fluctuations in the lead up. However, historically, volatility tends to decline after the election announcement as uncertainty is reduced and, in fact, the MSCI EM Index often shows positive performance in the 100 days following the election announcement. The long-term impact of the new government’s policy direction, particularly on the strength of the USD and foreign policy, is what is most crucial for emerging markets. Donald Trump has perhaps been a more vocal proponent of protectionism, proposing extreme measures, including minimum tariffs of 60% on Chinese goods, 10% tariffs on global imports and, most recently, 100% tariffs on countries that turn from the US dollar. However, Joe Biden has retained and expanded many of the tariffs implemented by Trump during his presidency, reflecting a rare area of agreement between the two adversaries and a broader US shift towards de-globalisation and protectionism. Given Kamala Harris’s role as Vice President in implementing and expanding key protectionist policies such as the Inflation Reduction Act (2022) and the CHIPS and Science Act (2022), significant changes in trade policy may not be expected if she takes office.

    Source: Bloomberg, figures are calculated from the first trading day after each country’s final election to 30 September 2024.

    As a result, we expect friend shoring and nearshoring to continue driving capital into regions like Mexico and ASEAN, particularly in their manufacturing sectors. Additionally, the US’s decoupling from China is likely to strengthen ties with allies such as Taiwan and South Korea for semiconductor chips, and with South American and Eastern European countries for raw materials such as lithium, benefiting these emerging markets’ respective industries.

    Geopolitics and Volatility

    Geopolitics has long been, and is likely to remain, a significant source of volatility in global equity markets. No market, whether developed or emerging, is immune to the impacts of geopolitical events such as trade wars, ongoing conflicts or rising regional tensions. We believe the key to navigating these shocks, much like economic crises, is to stay disciplined by continuously monitoring the situation, staying informed and revisiting and reconfirming every single investment case as circumstances evolve. A disciplined macro-overlay is essential in emerging market investing, even for bottom-up stock pickers like ourselves. This approach has allowed us to effectively navigate and mitigate risks associated with major geopolitical events. For instance, we had no exposure to Russia during its invasion of Ukraine, driven by concerns over governance issues and the regulatory environment.

    We closely monitor the relationship between China and Taiwan and believe that China will continue to focus on its own economic priorities in the near future, such as the overcapacity in the property market and high unemployment levels, and the recent measures to boost the economy seem to confirm this. Meanwhile, our exposure to Taiwanese companies is limited to asset-light businesses or those with a well-diversified global production base, providing some downside protection in the event of an escalation.

    Conclusion: Stay Calm and Carry On

    The bottom line is to stay disciplined and maintain a long-term perspective as markets tend to mean revert. Therefore, we believe by focusing on quality fundamentals rather than short term trends, volatility can be more effectively managed and even leveraged. In addition, falling interest rates have put EM back on the table as an attractive investment case for many, but we believe it is important to optimise EM investments via under-covered and mispriced small and mid-cap companies that will benefit from growing trends, such as AI, renewables and the growing consumer and middle classes, as well as diversifying your portfolio beyond the most concentrated stocks.

    ‍

    1 Bloomberg
    2 JP Morgan
    3 Statista
    4 Statista
  • Shortlisted: Citywire Investment Trust Awards 2024

    Shortlisted: Citywire Investment Trust Awards 2024

    We are pleased to announce that the Mobius Investment Trust has been nominated in the Global Emerging Markets category at the Citywire Investment Trust Awards 2024.

  • Shortlist: Investment Company of the Year Awards 2024

    Shortlist: Investment Company of the Year Awards 2024

    We are delighted to share that the Mobius Investment Trust has been shortlisted in the Emerging Markets category for Investment Week’s Investment Company of the Year Award 2024.

  • Understanding Market Volatility

    Understanding Market Volatility

    In the fifth episode of Insiders and Outliers, we dive into navigating market volatility in the wake of this August’s spike. MCP’s portfolio manager and founder, Carlos Hardenberg, shares insights from his decades of experience investing through major crises including the Asian financial crisis, the dotcom bubble, and the global financial crisis. We explore how volatility can present opportunities in undervalued companies, and examine the effects of interest rates, geopolitical risks, and currency fluctuations on market instability. Listen to the latest episode via the link below or on Spotify, Apple Podcasts and Soundcloud.

    To see our Podcast Policy go to www.mcp-em.com/en/podcast-policy