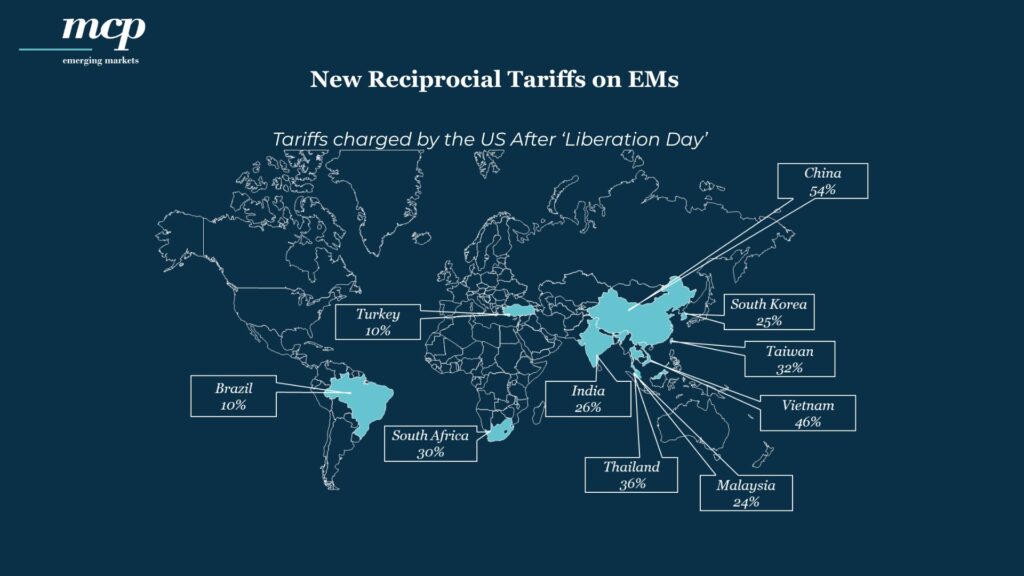
Donald Trump’s long anticipated tariff offensive was finally revealed yesterday on what he refers to as ‘Liberation Day’. We have mapped out the new tariffs impacting the EM countries where MCP is currently invested.
So far, these new tariffs have not significantly changed our outlook as the overall exposure of our holdings that export directly to the US in the affected sectors is limited. Notably, Trump has exempted certain sectors, such as semiconductors, where we maintain an overweight position. Likewise, our overweight exposure to the services sector, shielded from tariffs, adds to the resilience of our portfolio against these measures.
That said, we continue to remain cautious and watch the evolving situation closely, particularly any of Trump’s upcoming meeting with global leaders that could set a precedent for tariff negotiations. At the same time, we are monitoring potential indirect effects, such as an economic slowdown, shifts in global demand and supply chains or prolonged uncertainty in certain key sectors globally.
Our recent trips and direct engagement with portfolio companies in Taiwan, South Korea, and India further reinforce our confidence that the portfolio is well-positioned for the coming months.
On 11 March 2025, MCP Emerging Markets hosted a Zoom webinar where founding partner Carlos Hardenberg and investment analyst Swathi Seshadri provided an update on the strategy, performance and portfolio of the Mobius Investment Trust (MMIT).
The video below is a replay of the webinar.
Please email Anna von Hahn at anna@mcp-em.com should you have any questions or would like further information.
On 18 March 2025, MCP Emerging Markets hosted a Zoom webinar where founding partner Carlos Hardenberg and investment analyst Swathi Seshadri provided an update on the strategy, performance and portfolio of the Mobius Emerging Markets Fund (MEMF).
The video below is a replay of the webinar.
Please email Anna von Hahn at anna@mcp-em.com should you have any questions or would like further information.
Portfolio Manager, Carlos Hardenberg, and the MCP team are currently on-the-ground in Taiwan. So far, they have had company meetings with:
All of MCP’s Taiwanese holdings
Foundries
IC design houses, incl. ASIC
Silicon IP
Server assemblers
Material & component manufacturers
Private companies looking to IPO soon
Here are some key facts about the country that we find particularly interesting:
Semiconductor Industry:
1. TSMC held a 64.9% share of global semiconductor foundry revenue in Q3 2024, a 12% YoY increase. Including other foundries, Taiwan’s total market share surpassed 72%, up 9% YoY1.
2. The global semiconductor market has experienced significant growth, nearly doubling over the past decade. According to Gartner, revenues reached $626 billion in 2024, with forecasts predicting an increase beyond $700 billion in 20252.
Taiwan’s Economy:
3. Taiwan’s GDP grew by approximately 4.3% in 2024, bringing per capita GDP to around $34,000. Economic growth is projected to continue at a rate of 3.1-3.3% in 20253.
4. Taiwan’s government debt-to-GDP ratio has steadily declined over the past decade, standing at 26% in 2024. In comparison, the U.S. debt-to-GDP ratio exceeds 120%4.
Taiwan’s Trade:
5. Taiwan’s exports surged by 32% YoY in February 2025, marking the strongest growth since February 20225.
6. In 2024, Taiwan recorded a net trade surplus of $80 billion6.
7. Despite geopolitical tensions, Taiwan and China maintain robust trade relations and FDI flows. China remains Taiwan’s largest trading partner, although Taiwan ran a $70 billion trade surplus with China in 20247.
More Facts!
8. Taiwan is recognised as a highly liberal and democratic nation, with a score of 94/100 in the Freedom House rankings8.
9. Taiwan is officially recognised by only 12 countries, most of which are small island nations9.
10. Taiwan has four official languages and over 20 living languages.
Footnotes:
1 Statista
2 Gartner
3 Statista
4 IMF
5 Trading Economics
6 Statista
7 Statista
8 Freedom House
9 Ministry of Foreign Affairs, Republic of China (Taiwan)
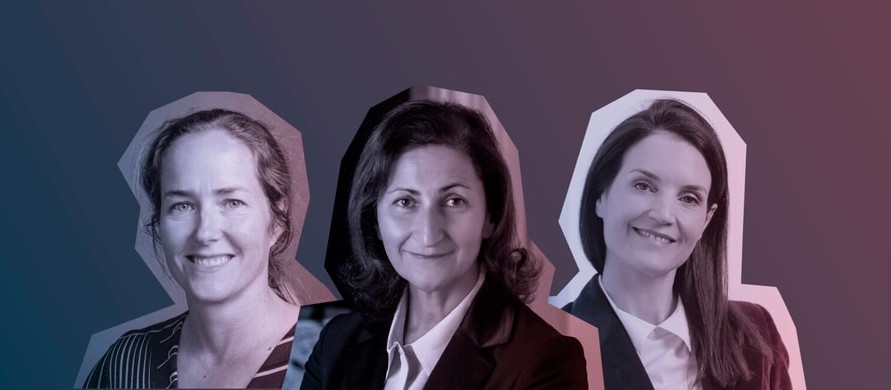
On the occasion of Women’s Day, celebrated on March the 8th, RankiaPro take a look at how the sector is evolving and how we are all making an effort to achieve greater gender parity, collecting the testimonies of three leading female professionals in the industry, including our Head of Investor Relations, Anna von Hanh, along with Maxime Carmignac and Rose Ouahba from Carmignac.
Anna’s Testimony:
My journey into finance was anything but typical. After 15 years in book publishing, I made the leap into the financial world—a shift that quickly revealed stark gender disparities between industries. For over a decade, I attended the Frankfurt Book Fair, where, based on my own observations, women seemed to make up around 80% of people working there. Now, instead of strolling through the book fair, I find myself traveling just 70 kilometers further to a finance fair in Mannheim, where the ratio appears exactly reversed. The contrast made me question why finance remains so male-dominated and what can be done to change that.
For generations, women have been underrepresented in finance. Girls are less frequently introduced to financial topics, and societal expectations continue to influence career choices. Many women gravitate toward creative (often less well paid) industries, possibly not only out of preference but also due to ingrained perceptions that men should be the primary earners. Meanwhile, men face pressure to pursue high-paying roles, reinforcing a gender imbalance in finance and investment.
A bias within the industry might be compounding this disparity. A 2021 CFA Institute study found that over three-quarters of women in investment believe the field is biased toward men, particularly in recruitment, promotions, and workplace culture. Addressing this requires systemic change, starting with early financial education. All schools should introduce finance and investment topics to both boys and girls, and women in the industry should be visible role models to inspire the next generation.
Even within finance, women are more commonly found in marketing and client relations rather than investment roles, further limiting women’s influence in financial decision-making. Yet, research shows that diverse teams make better decisions. Studies indicate that investment teams in the top quartile of gender diversity outperform those in the bottom quartile by 45 basis points annually. Despite this, only 12.5% of global fund managers are women, a figure that has barely changed in the past decade.
I have observed that women in finance tend to question themselves more, which can sometimes be seen as a lack of confidence. However, I believe, in investing, this self-reflection is an asset—it encourages deeper analysis, continuous reassessment, and a more balanced approach to risk. I have seen cases where overconfidence led to emotional attachment to an investment thesis, preventing rational decision-making. Encouraging diversity in investment teams fosters a broader range of perspectives, better risk management, and ultimately stronger performance.
At MCP, we are fortunate to have a 50/50 gender split within the team, and in my experience, this dynamic works exceptionally well. Yet, challenges persist—women still bear more childcare responsibilities, impacting career progression. While outsourcing is an option, many prefer to be present, particularly as children face growing digital distractions.
The COVID-19 pandemic briefly reshaped workplace dynamics, providing more flexibility. However, the recent push back to office-based work risks reversing this progress, making it harder for women to balance work and family. Companies that embrace flexibility will retain more skilled professionals, fostering a more diverse and resilient workforce.
Progress has certainly been made, but there’s still a long way to go. In some parts of the world, we’re even seeing signs that gender equality could be slipping backward. I truly hope that’s not the case—for the sake of my daughter and her generation. The future of finance will be stronger, more innovative, and more resilient with women fully included.
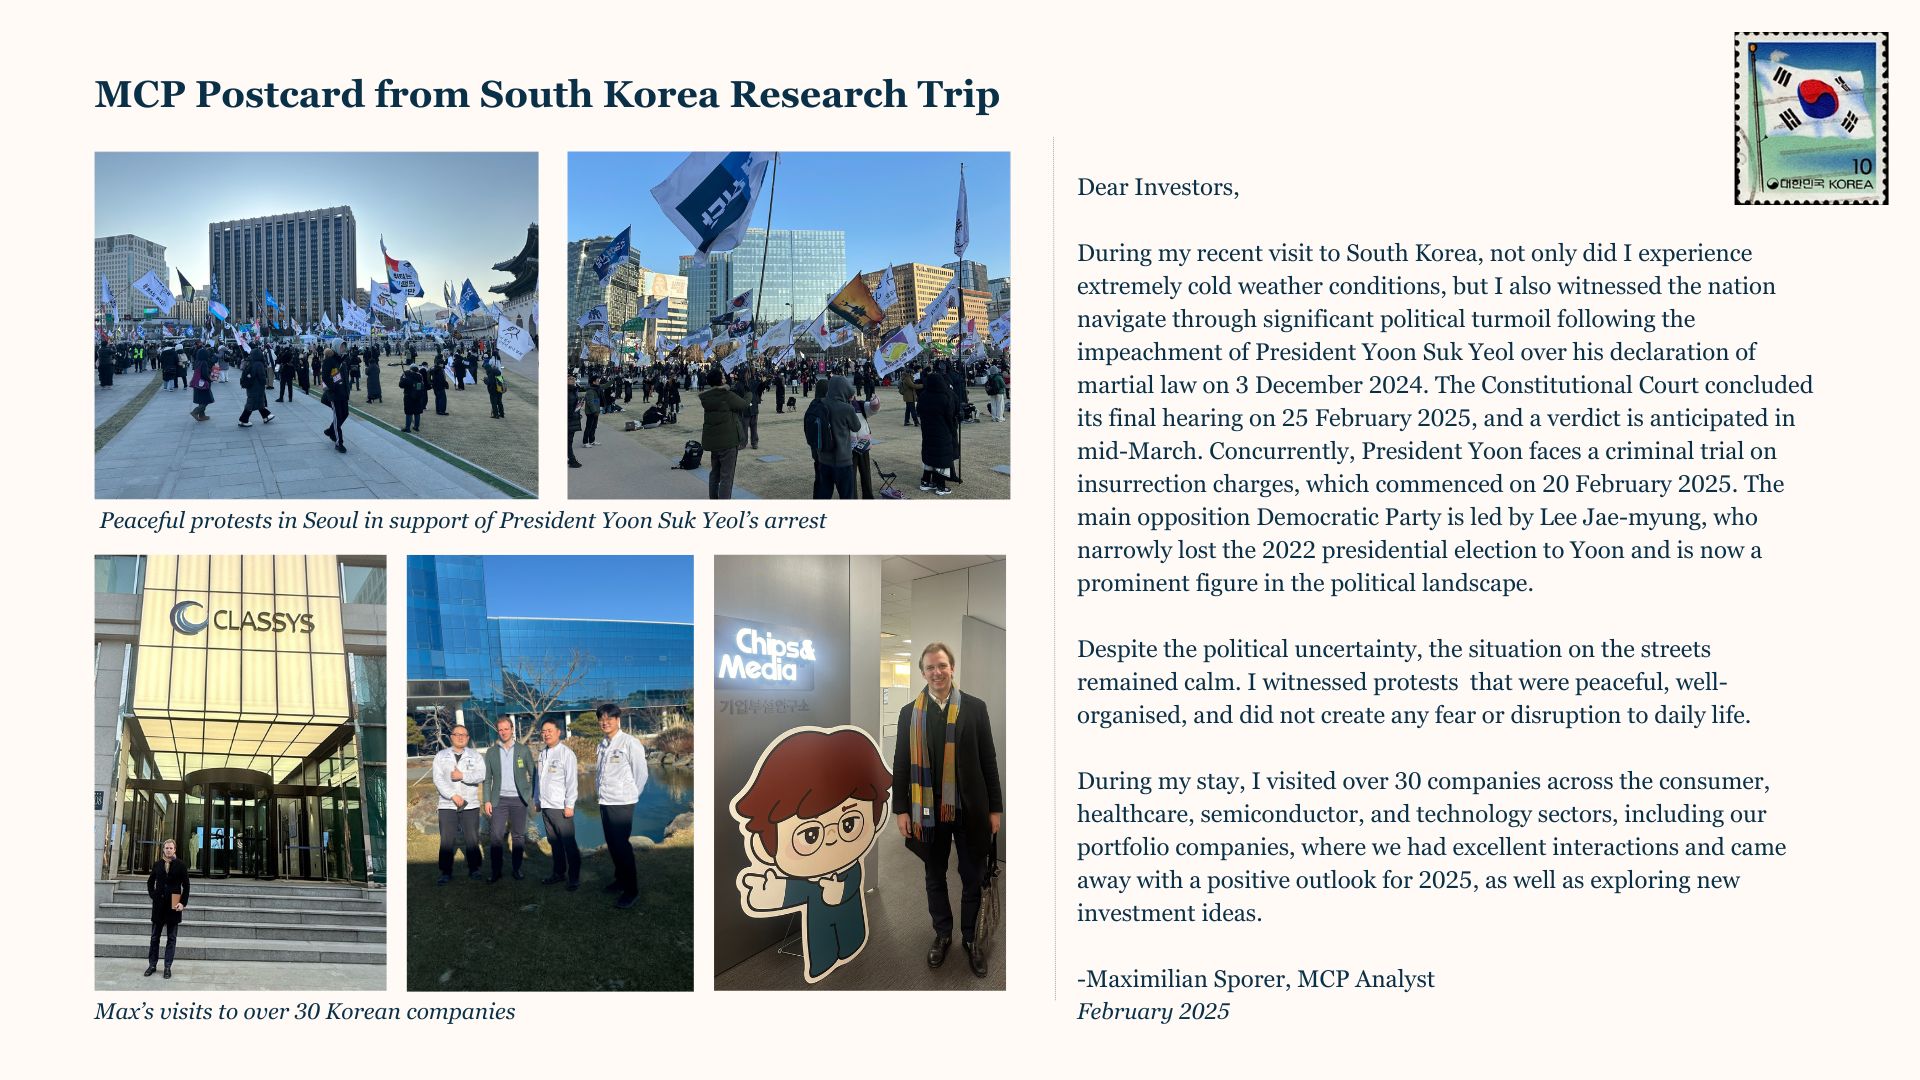
During my recent visit to South Korea, not only did I experience extremely cold weather conditions, but I also witnessed the nation navigate through significant political turmoil following the impeachment of President Yoon Suk Yeol over his declaration of martial law on 3 December 2024. The Constitutional Court concluded its final hearing on 25 February 2025, and a verdict is anticipated in mid-March. Concurrently, President Yoon faces a criminal trial on insurrection charges, which commenced on 20 February 2025. The main opposition Democratic Party is led by Lee Jae-myung, who narrowly lost the 2022 presidential election to Yoon and is now a prominent figure in the political landscape.
Despite the political uncertainty, the situation on the streets remained calm. I witnessed protests that were peaceful, well-organised, and did not create any fear or disruption to daily life.
During my stay, I visited over 30 companies across the consumer, healthcare, semiconductor, and technology sectors, including our portfolio companies, where we had excellent interactions and came away with a positive outlook for 2025, as well as exploring new investment ideas.
Since our inception, there has rarely been a dull moment, and 2024 was no exception. While a global election year would naturally bring a degree of unpredictability, many of the year’s most significant surprises and sources of volatility stemmed from elsewhere, ranging from speculation around rate cuts and tech-driven market movements to Chinese stimulus measures— alongside the backdrop of the US election.
Amidst the turbulence, one of the more encouraging developments has been the ability of several developed and emerging markets to successfully steer towards what appears to be a soft landing, accompanied by the gradual (albeit occasionally uneven) normalisation of global inflation. While some fluctuations may still occur, the overall trend of easing inflation pressures, with only a few exceptions, seems clear.
For the MCP team, 2024 was a productive year, marked by extensive research trips to key markets resulting in several new additions to our portfolio. In-person meetings with companies, their competitors, local experts, politicians and economists inform our deep understanding of companies, and are an invaluable tool for conducting due diligence on investment ideas.
During these conversations and in follow-ups afterwards, we received positive updates from several companies in our portfolio that confirm our outlook. For example, Elite Material, a leading producer of semiconductor materials, is preparing to supply its upgraded M8 material for a US cloud service provider’s ASIC (Application-Specific Integrated Circuit) in 2025, addressing the growing demand for AI processing and the need for customised solutions over NVIDIA’s GPUs (Graphics Processing Unit). Similarly, Chroma has developed a unique device for its foundry client’s advanced packaging processes, ensuring precise alignment of stacked chip components, an essential capability for manufacturing next-generation AI chips.
Over the year, MEMF was able to generate robust outperformance returning 5.4% (Private C USD Founder) and 11.9% (Private C EUR Founder). In Q4, MEMF returned -2.3% (Private C USD Founder) and 5.0% (Private C EUR Founder), outperforming the benchmark (MSCI EM Mid Cap Index Net TR) by 6.5% (USD) and 7.0% (EUR) respectively.
The final quarter of 2024 has largely been defined by Donald Trump’s election victory, prompting businesses and governments worldwide to prepare for the implications of his second presidency. Additional key developments influencing emerging markets this quarter include the Fed’s second and third rate cuts of the year, the South Korean president’s controversial attempt to impose martial law, and the announcement of further stimulus measures in China aimed at bolstering economic growth.
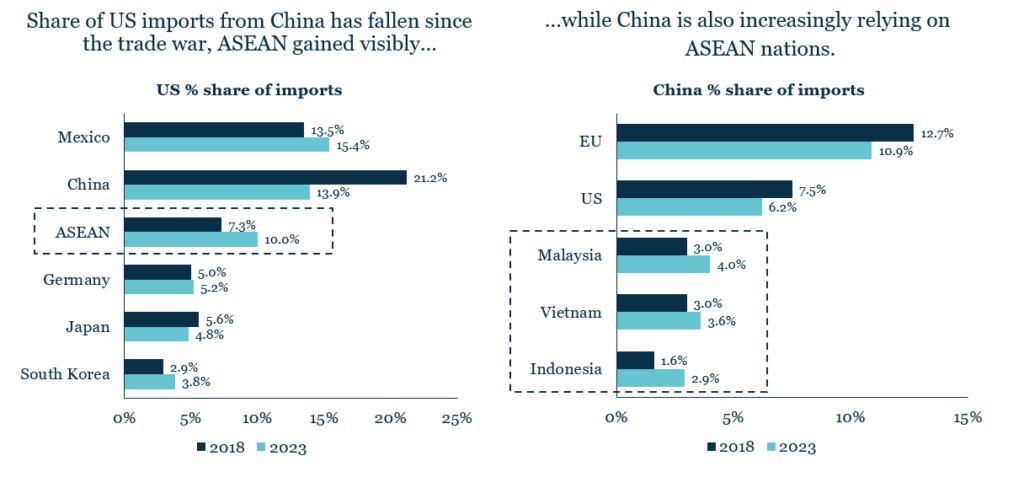
Donald Trump’s landslide victory and Republican control of Congress mark a pivotal shift for the US and global markets. While US equities and the dollar have strengthened in response, emerging markets face a more uncertain outlook due to Trump’s aggressive tariff rhetoric. Yet, as Einstein suggested, within difficulties lie opportunities. Countries like India, Indonesia and Vietnam, are already benefiting from the “China+1” strategy and appear well-positioned to attract new manufacturing investments. Their competitive labour markets, improving infrastructure and supportive government policies make them increasingly appealing, as companies seek to diversify supply chains and reduce dependency on China. At the same time, the US’s heavy reliance on imports, particularly from China, reduces the likelihood of sweeping tariffs, which could risk significant domestic disruption. Nevertheless, Trump’s track record and rhetoric on trade raises the possibility of bold policy shifts that may reshape global trade dynamics in the years to come.
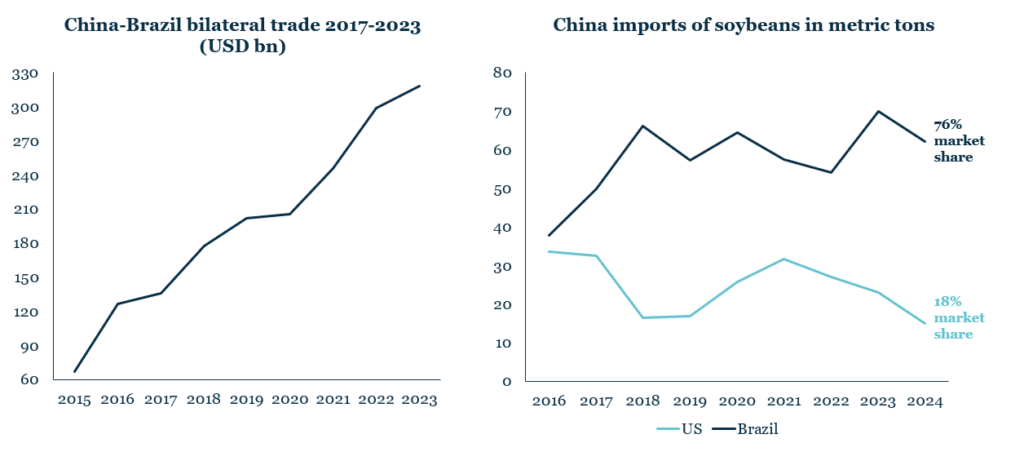
Emerging markets have previously responded to the above dynamics with increased trade diversification and reduced reliance on the US dollar. During the 2018 trade war, for example, China shifted imports like soybeans to Brazil, a move that fuelled record bilateral trade. This pattern could reemerge under Trump’s renewed tariff threats.
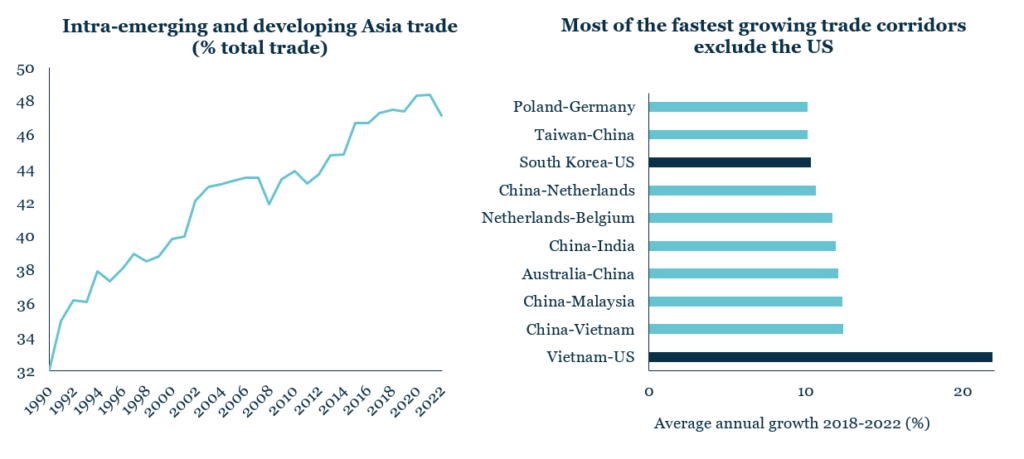
Rising Intra-EM Trade Reduces Dependence on US Trade
Source: Asia Regional Integration Centre, Economist Impact calculations, Financial Times. As of 31 December 2024.
Additionally, nations such as India are advancing local currency trade agreements, fostering resilience against external shocks. Intra-EM trade, particularly within Asia, set to rise from $4.3 trillion in 2023 to $7.1 trillion in 2030 (HSBC Forecast), has also grown significantly and is poised to accelerate further, offering emerging markets the chance to deepen their autonomy and global influence.
Brazil-China Trade Grows as China Diversifies from the US
Source: Reuters, Statista. As of 31 December 2024.
ASEAN Macro
Source: Maybank Research, Bloomberg, local sources. As of August 2024
Monetary policy adds another layer to this evolving landscape. Inflation has moderated over the past year, following the Federal Reserve’s earlier rate hikes. This had created room for monetary easing in 2024, with a cumulative 75bps rate cut signalling a shift in policy. However, the strength of the US economy may slow the pace of future reductions, even if the overall direction seems clear. Lower rates provide emerging market central banks with room to ease monetary policy, enabling cheaper borrowing, improved consumer sentiment and increased corporate investment. At the same time, local conditions remain pivotal. Brazil, for example, continues to raise interest rates to combat inflationary pressures. Nevertheless, we believe the country still holds attractive long-term opportunities, particularly in quality companies with strong fundamentals.
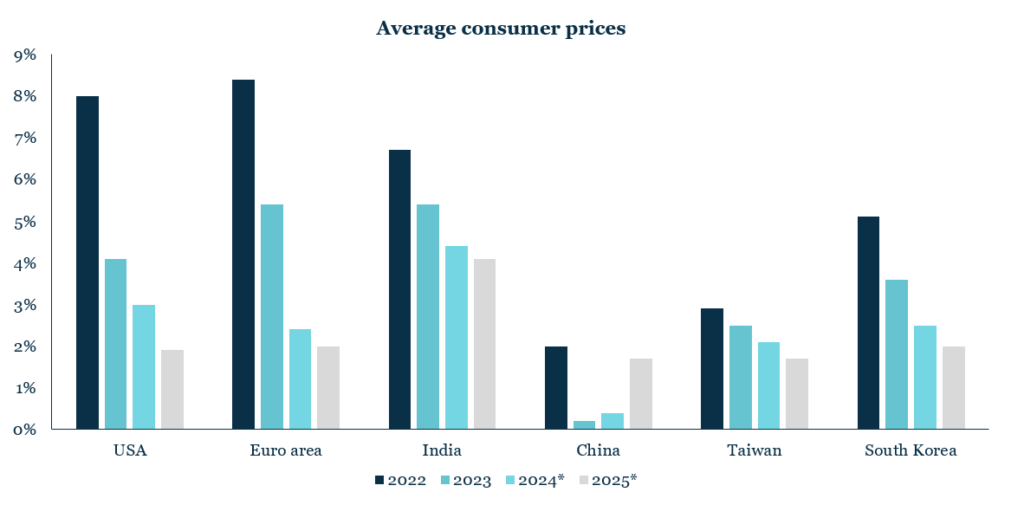
Global Inflation is Normalising
Source:IMF WEO October 2024, * indicates forecast
China, meanwhile, continues to grapple with significant economic challenges of its own, including its property sector crisis, weak consumer sentiment, and deflation. Recent stimulus measures, including a $1.4 trillion plan to address hidden debt and monetary easing, have provided only short-term relief. However, deeper structural reforms remain essential. The Politburo’s efforts to boost domestic demand and stabilise the property sector are positive signals, particularly in light of potential US tariff increases, but caution remains warranted.
Geopolitics remains an ongoing risk, with tensions in the Middle East, the Russia-Ukraine war, and China-Taiwan relations posing significant challenges. Our disciplined macro-overlay has been instrumental in navigating these complexities. This approach will remain central as we navigate 2025. On the positive side, Trump’s leadership may offer the potential to de-escalate conflicts and foster peace negotiations—a trend that may already be emerging in the Middle East at the time of writing.
Taken together, these interconnected factors paint a complex picture for 2025. While risks are evident, emerging markets could leverage this period of transition to strengthen resilience, diversify trade and attract investment, positioning themselves as key drivers of global growth in the years ahead. Furthermore, emerging markets are essential for diversification, offering strong growth potential, attractive valuations and innovative companies that play a key role in global supply chains. This is particularly important as the US market, with the S&P 500 heavily concentrated in just seven companies which were accounting for around 28% of its market capitalisation at the end of 2024 and contributed over 50% of its returns during the year, poses significant concentration risks. Active investing in emerging markets allows for another layer of diversification by identifying lesser-covered companies, which may offer unique opportunities for long-term growth and the potential to outperform broader market trends.
Heading into 2025, we remain focused on our long-term strategy and the core fundamentals of our holdings. Conversations with our portfolio companies in recent months have reinforced our cautiously optimistic outlook for 2025 and beyond.
As Lunar New Year celebrations continue this week, it presents an opportunity to reassess the Chinese market. The Snake, whose symbols include wisdom, transformation, and strategy, serves as a hopeful emblem for China as it navigates ongoing structural challenges this year.
The economy remains under pressure, grappling with a property sector crisis, weak consumer sentiment, and deflation. In response, Beijing has signaled plans for further stimulus measures beyond those introduced late last year, including a $1.4 trillion plan to address hidden local debt and monetary policy easing. These are certainly positive steps but have so far provided only short-term relief. Given the depth of China’s economic challenges, which we believe will take years to resolve, more strategic and decisive action appears to be the wise course for Beijing in 2025. The upcoming annual CPPCC National Committee meetings in early March will be a key event to monitor for further announcements of potential stimulus and domestic support measures.
Beyond the New Year, there is limited cause for celebration this week as today an additional 10% tariff on Chinese imports to the US will take effect indefinitely. While this increase is lower than many anticipated, especially compared to Trump’s threats on the campaign trail, it is likely to spur market volatility as speculation grows over further tariff increases and their timing.
Beijing has said it will legally challenge the tariffs as they violate World Trade Organization rules and today announced it will impose additional tariffs between 10-15% on a basket of US imports, including, but not limited to, oil, gas, and farming equipment.
Overall, while the Year of the Snake represents transformation, we maintain our cautious outlook and underweight position in the Chinese market given the significant domestic and global challenges the country faces. Instead, we prefer indirect exposure to the country through Korean and Taiwanese companies that have better corporate governance and operate in a more stable macroeconomic and regulatory environment. However, China remains the world’s second-largest economy, with its 2024 GDP growth having meet its 5% target, outpacing most developed and even emerging markets growth. Therefore, amidst caution, we still search for exciting investment opportunities that meet our quality investment criteria.
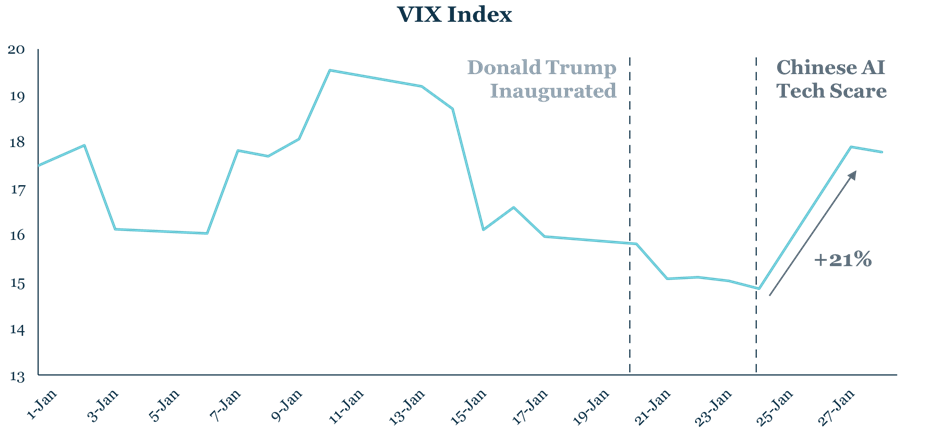
Yesterday, market volatility, measured by the VIX Index, jumped 21% from the previous trading day’s close. This spike was triggered by DeepSeek, a Chinese AI start-up, unveiling a large language model (LLM) reportedly built with just USD$6M, challenging the long-standing assumption that AI development requires vast amounts of expensive Nvidia chips. As a result, Nvidia’s share price dropped 17% on Monday with sell-offs reaching across U.S. big tech with other ‘Magnificent 7’ companies experiencing smaller, yet notable, declines.
Source: Bloomberg
This underscores the risks of a highly concentrated market where sell-offs can become more severe as many investors rush to offload the same stocks, leading to outsized losses for those who remain invested.
While the high concentration of the U.S. market is well-known, it’s less widely recognised that a similar dynamic exists in emerging markets. In the MSCI Emerging Markets Index, the top 10 companies make up roughly 25% of the total index weight despite having around 1,300 constituents. Additionally, many bulge-bracket EM funds are heavily weighted toward these top 10 names, potentially increasing their vulnerability to significant drawdowns during market sell-offs.
This highlights the importance of portfolio diversification. Instead of over-concentration in a few dominant players, MCP focuses on smaller, innovative companies in emerging markets, particularly in sectors like AI and the semiconductor supply chain as well as those catering to the global recovery in consumer demand. These are areas we believe have strong potential to generate alpha and provide long-term growth opportunities.